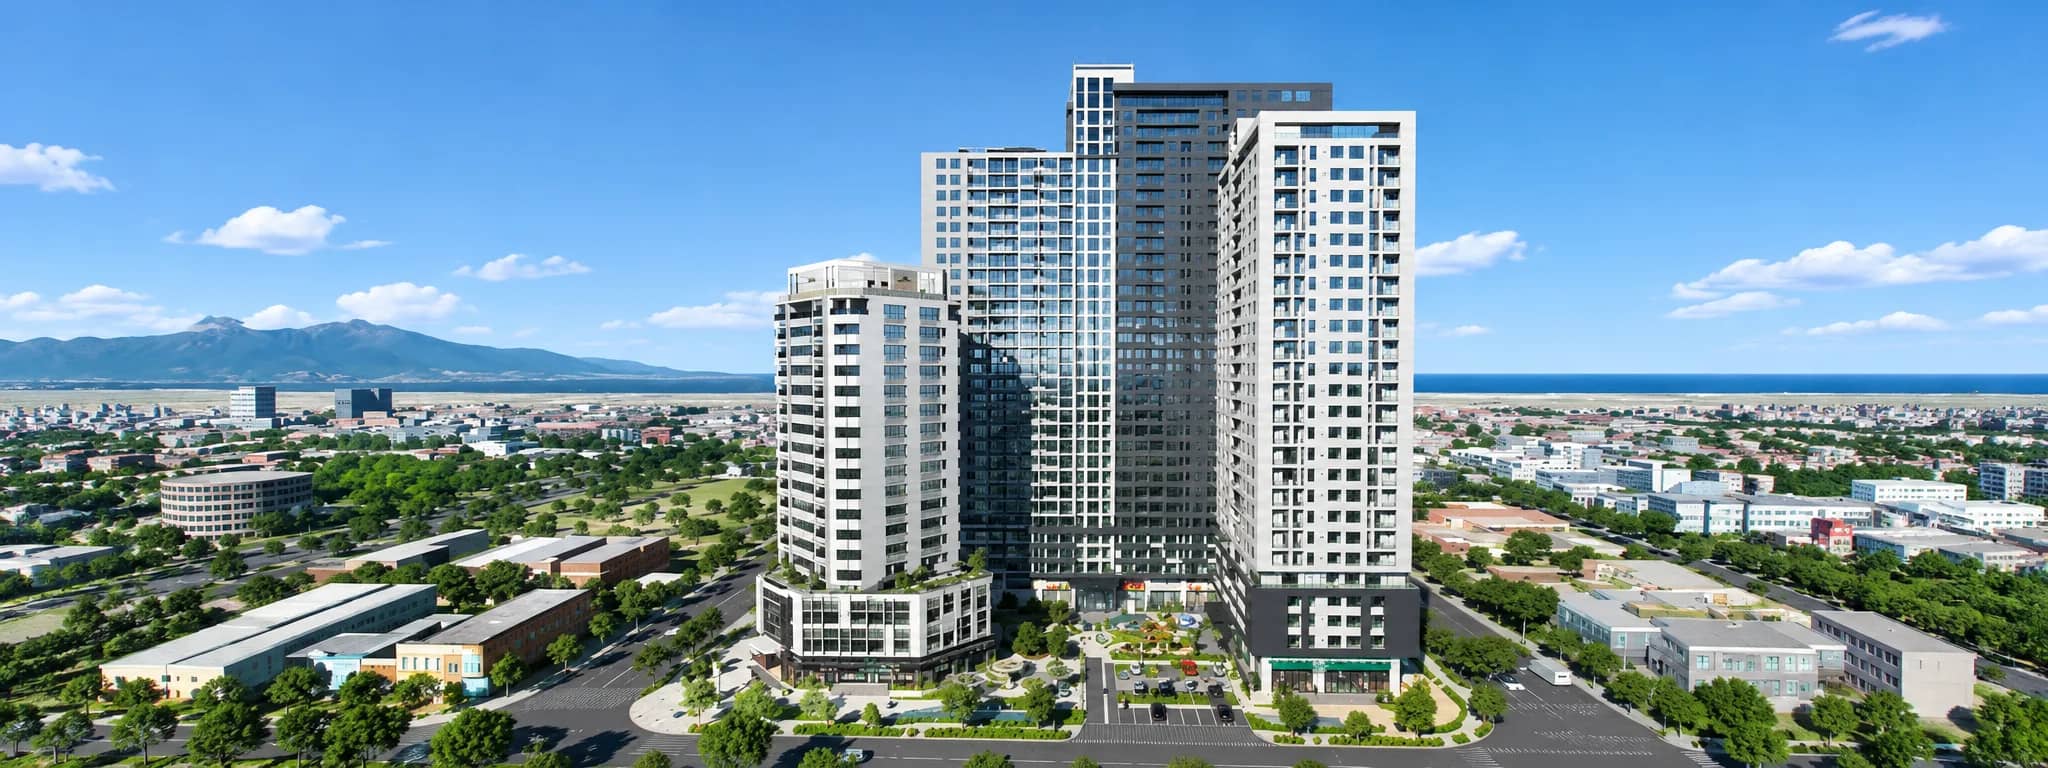
DKRA's Q3/2026 data shows that the Da Nang apartment market has slowed down. This is when buyers have the bargaining advantage, but they need to choose projects more carefully.
Table of contents
After an active first half of the year, the Da Nang apartment market entered Q3/2026 with a noticeably slower pace. This article summarizes key figures from the DKRA Consulting report, along with practical leasing perspectives from Đất Vàng Group, to give genuine homebuyers and investors more grounds for decision-making.
Key figures of Q3/2026
According to DKRA Consulting (published on October 23, 2026):
- Primary apartment supply: 4,385 units from 20 projects, down 14% compared to the previous quarter
- New launch supply: down nearly 40% compared to Q2/2026
- Absorption volume: 2,099 units, down 25% compared to the previous quarter and 24% year-on-year in 2025
- Grade B (mid-end) apartments account for 46% of supply but up to 68% of absorption
Regarding prices, sources recorded relatively stable primary prices, accompanied by various demand-stimulating policies. Transactions concentrated in new projects with a general level of about 60–70 million VND/m². Secondary prices (resales) showed a slight downward adjustment of about 3–5%.
How to read these figures?
Buyers are becoming more selective
Liquidity has decreased, but the mid-end segment still accounts for the majority of transactions. This shows that buyers are not leaving the market, but shifting to affordably priced products with clear living or rental demand.
Brand reputation and legal status are prioritized
During a slow market phase, projects from major developers with clear legal status and committed progress still retain their appeal. New projects in Da Nang such as Capital Square (BRG Group) or Sun Saphia Residence, S-Light Tower, FourS Tower (Sun Group) all belong to this group.
Buyers hold the bargaining advantage
When new supply decreases and developers roll out demand-stimulating policies, buyers have more time to compare and negotiate: discounts, extended payment schedules, and interest rate support.
Perspective from the rental market
While the sales market has slowed down, the demand for fully furnished apartments in the city center and along the Han River remains stable, especially from foreign guests. As of mid-November 2026, the apartments managed for rent by Đất Vàng Group have the following prices:
- Studio: from 15.5 million VND/month
- 1 bedroom: 22–25 million VND/month
- 2 bedrooms: 16–35 million VND/month
For investors, this is crucial information to calculate rental cash flow before buying, rather than just expecting price appreciation.
What should buyers do right now?
- Buy to live: take advantage of the slow period to carefully choose units and negotiate favorable policies
- Buy to rent: choose central locations, near the beach or river, with moderate unit sizes (studio, 1–2 bedrooms) as they are the easiest to rent out
- Avoid concentrating all capital into a single product, carefully calculate debt repayment capacity if borrowing from a bank
- Check the legal status and project progress before placing a deposit
Outlook for Q4/2026
DKRA forecasts that Q4/2026 will see about 500–1,000 newly launched apartments, with demand not improving significantly. In the medium term, factors such as the Da Nang Free Trade Zone and the International Financial Center (launched on January 9, 2026) are expected to generate additional living and rental demand from experts and foreign investors.
Need advice on choosing an apartment to live in or invest for rent? The Đất Vàng Group team is ready to assist with actual data from the apartments we manage.
Reference sources: DKRA Consulting, Da Nang market report for Q3/2026 (via baodautu.vn, batdongsan.baoxaydung.vn); Da Nang City Electronic Information Portal.
Apartment management, operation, and leasing unit in Da Nang. We share market data, rental, purchase, and apartment consignment experiences from our daily practical work.